Documents That Age Without Warning: An Annual Identity File Review for UK Crypto Accounts
Most discussions of crypto risk open with volatility and close with custody. Less attention is given to a quieter failure mode: an account that verified without difficulty two years ago and now stalls at the withdrawal screen, not because anything was compromised, but because a passport has lapsed or a utility bill still carries an address the holder left behind.
For UK users, this is an administrative risk rather than a market one, and it is largely manageable with a small amount of forward planning. What follows is a practical account of what firms ask for, why the file drifts out of date, and how to review it once a year without drama.
Verification is a state, not an event
Firms supervised in the UK under the Money Laundering, Terrorist Financing and Transfer of Funds (Information on the Payer) Regulations 2017 are expected to apply a risk-based approach and to keep customer due diligence current, rather than collecting it once at onboarding and filing it away. In practice, that produces two kinds of review. Some firms work to a fixed cycle, often every twelve or twenty-four months. Others act on triggers: a withdrawal above a threshold, a change of bank account, a new residential address, or a transfer to a self-hosted wallet that falls within the travel rule expectations now applied to UK cryptoasset transfers.
The consequence is straightforward. Being verified is a condition that has to be maintained, and the evidence supporting it has a shelf life.
The four items a reviewer actually reconciles
Although forms vary between platforms, most reviews come back to a small set of documents and to whether they agree with one another.
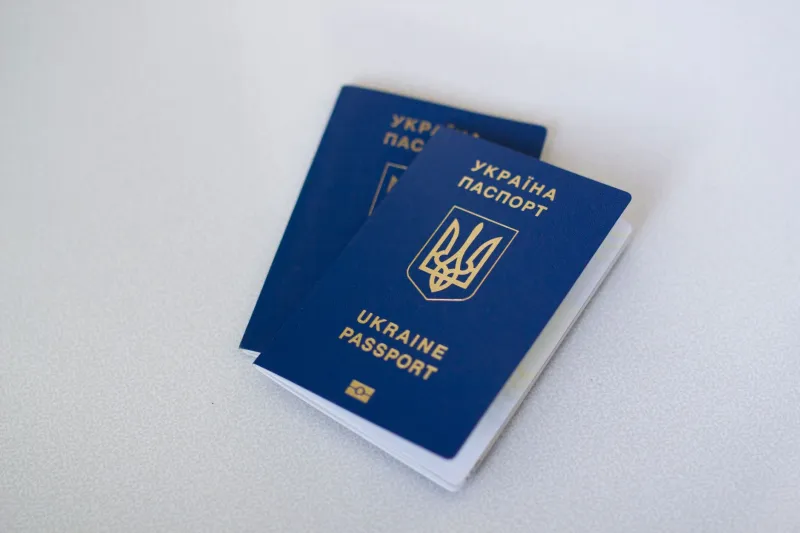
Photographic identification. A passport or photocard driving licence, in date, legible, with all four corners visible and no glare across the machine-readable zone. Expiry matters: a passport that lapsed last month is no longer acceptable identification, even if it was accepted a year ago.
Address evidence. Typically a bank statement, council tax bill or utility bill issued within the last three months. The name and address must match the account record exactly, including any flat number, and the document should be a full page rather than a cropped strip.
A liveness check or selfie. Increasingly automated, and increasingly sensitive to drift between the photograph on file and the person in front of the camera. A change of hairstyle is harmless; a change of surname is not.
Source of funds or source of wealth. Requested more often at review than at sign-up, particularly where deposit patterns have changed. Salary slips, a savings statement or the completion statement from a property sale are the usual answers.
The house move that breaks the file without a sound
Address is the most common point of failure, and it usually fails quietly. A holder moves, updates the bank and the electoral roll, and forgets the exchange. Nothing happens for months. Then a withdrawal is held and the request for current address evidence reveals a mismatch that has been sitting in the account since the move.
Shared tenancies complicate this further. Where the council tax bill or energy account sits in a flatmate's name, the obvious documents are unavailable. Workable alternatives include a personal bank statement, a letter from the letting agent on headed paper, or a provisional driving licence updated to the new address. It is worth confirming which of these a given platform accepts before a review is under way rather than during one.
Names, and the order in which to change them
Where a name has changed through marriage, civil partnership or deed poll, the sequence matters. Update the bank and the driving licence first, then the exchange, and submit the supporting certificate alongside the new identification. A file that shows a new surname on a passport and an old one on the bank statement will be queried regardless of how well documented the change is elsewhere.
A one-hour review, once a year
A single scheduled session removes most of the surprise. Choose a date that already means something — a birthday, the turn of the tax year, the first weekend of October — and repeat it annually.
- List every platform holding an account in your name, including dormant ones with small balances.
- Record the expiry date of the identification on file for each.
- Note when address evidence was last submitted, and whether it still reflects where you live.
- Check that the bank account linked for deposits and withdrawals is still open and still yours.
- Confirm that the email address and mobile number on each account are current, since these are the recovery routes if a review goes wrong.
- Keep a dated note of the last refresh, so that a future request for information does not arrive as a complete surprise.
On privacy: send what is asked, not what is convenient
A review is a request for specific documents, not an invitation to hand over a decade of financial history. Supply the items listed, redact only what is unconnected to the request — a statement showing unrelated transactions, for instance — and accept that heavy redaction may be rejected and re-requested.
Two habits are worth adopting. First, submit documents through the platform's own secure channel rather than by email attachment or, worse, a direct message on social media; no legitimate firm asks for a passport photograph in a chat window. Second, be sceptical of unsolicited approaches that cite a review as a pretext for collecting documents.
If verification does not go through
Failures are usually mechanical: a blurred image, an out-of-date bill, a name mismatch. Read the stated reason carefully and respond to that point alone, through the support channel, quoting any ticket reference. Keep copies of everything submitted and every reply.
Where a firm is within the jurisdiction of the Financial Ombudsman Service, a complaint that remains unresolved after eight weeks can be escalated there. Coverage is not universal across the crypto sector, so it is worth establishing in advance what a particular provider's complaints route actually is.
A small test before it matters
Finally, consider a modest withdrawal while nothing depends on it. A small transfer that clears without friction is a far better indicator of account health than a reassuring dashboard, and it converts an abstract worry about paperwork into a known quantity. The file, like the account, should be tested while the outcome is unimportant.